Investing
Best Online Investment Platforms for Beginners: Fees & Features
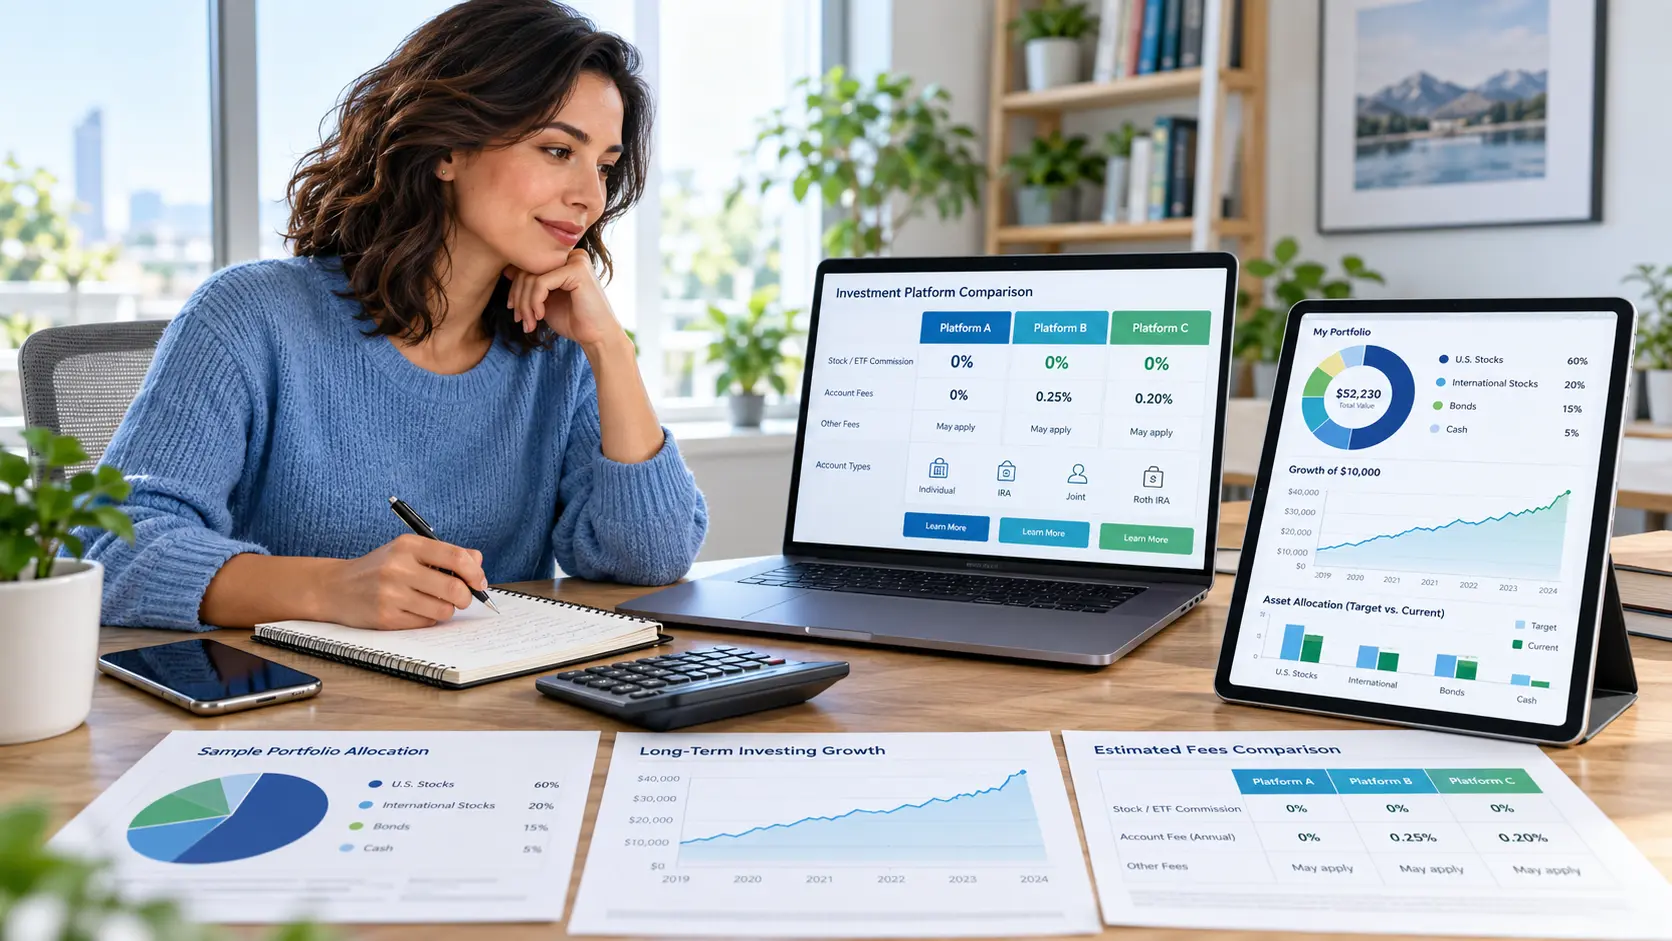
Starting to invest has become much easier than it was a generation ago. You no longer need to call a broker every time you want to buy a stock or have a large amount of money before opening an investment account. Many online investment platforms now offer low or zero account minimums, commission-free trading for certain investments, mobile apps, automated investing, educational resources, and access to diversified funds.
That convenience creates a different problem: beginners now have an enormous number of platforms to choose from.
One brokerage may emphasize simplicity and fractional shares. Another may provide extensive research and retirement accounts. A third may focus on automated portfolio management. Some platforms charge no commission for ordinary stock trades but charge for options, account transfers, advisory services, mutual funds, or other activities.
The best online investment platform for a beginner is therefore not simply the app with the most attractive interface or the one advertising "$0 trades." The right platform should match your investment goals, account type, preferred investments, level of guidance, expected account balance, and willingness to manage your own portfolio.
This guide explains how beginner investors can compare online investment platforms by fees, features, account types, investment choices, automation, research tools, security, and customer support before opening an account.
What Is an Online Investment Platform?
An online investment platform is a digital service that allows you to open an investment account, deposit money, buy or sell investments, monitor your portfolio, and manage your account through a website or mobile application.
Depending on the provider, a platform may allow you to invest in:
- Stocks
- Exchange-traded funds (ETFs)
- Mutual funds
- Bonds
- Treasury securities
- Options
- Certificates of deposit
- Money market products
- Fractional shares
- Managed portfolios
Some platforms operate mainly as self-directed brokerages. Others offer automated investment management, commonly referred to as robo-advisory services. Large financial firms may provide both.
What Makes an Investment Platform Beginner-Friendly?
A beginner-friendly platform should make investing easier to understand without hiding important risks or costs.
Useful features can include:
- Low or no account minimum
- Low trading costs
- Fractional shares
- Automatic recurring investments
- Easy-to-understand portfolio information
- Educational resources
- Retirement account options
- ETF and mutual fund research tools
- Responsive customer service
- Strong security features
- Clear fee disclosures
More features are not always better. A new investor who wants to contribute $200 every month to diversified index funds may have little need for professional trading charts, complex options tools, or margin borrowing.
The goal is to find a platform that supports the investing behavior you actually intend to follow.
1. Understand the Different Types of Investment Platforms
Before comparing brands, understand the major categories of investment services.
Self-Directed Brokerage Platforms
A self-directed brokerage lets you choose and manage your own investments.
You decide what to buy, when to invest, and when to sell.
This model may be appropriate for investors who want to build their own portfolios using stocks, ETFs, mutual funds, bonds, or other securities.
Many large online brokerages now offer commission-free online trading for listed U.S. stocks and ETFs, although other charges can still apply.
Robo-Advisors
Robo-advisors automate much of the portfolio-management process.
You typically answer questions about your:
- Investment goal
- Time horizon
- Risk tolerance
- Financial circumstances
The service then recommends or manages a diversified portfolio, often using ETFs.
Robo-advisors may charge an annual advisory fee or a recurring subscription fee. That fee is separate from the expense ratios charged by the funds held inside the portfolio.
Full-Service or Advisory Platforms
Some investors want access to a human financial professional who can provide ongoing advice.
Advisory accounts often charge fees based on the amount of assets managed, although other pricing arrangements are also possible.
This can provide more assistance but may cost more than managing a simple portfolio yourself.
2. Compare Trading Commissions
Trading commissions used to be one of the largest costs facing ordinary investors. Today, many U.S. online brokerages charge $0 commissions for online trades of listed U.S. stocks and ETFs.
That does not mean every trade is free.
Depending on the platform and security, investors may encounter charges for:
- Options contracts
- Broker-assisted transactions
- Certain mutual funds
- Over-the-counter securities
- Foreign securities
- Futures
- Fixed-income transactions
- Regulatory fees
If you only plan to buy broad-market ETFs periodically, your transaction costs could be very low. If you expect to trade specialized investments, the fee schedule becomes much more important.
3. Remember That "$0 Commission" Does Not Mean "$0 Cost"
This is one of the most important lessons for beginners.
A brokerage can advertise commission-free stock trading while still charging other fees.
Possible costs include:
- Fund expense ratios
- Advisory fees
- Account transfer fees
- Wire fees
- Options contract fees
- Margin interest
- Broker-assisted trade fees
- Foreign transaction fees
- Certain mutual fund transaction fees
The U.S. Securities and Exchange Commission explains that investment fees reduce the amount of money remaining in your portfolio to generate future returns. Beginners should therefore consider both platform-level costs and investment-level costs.
You can read the SEC's investor education material about fees at Investor.gov.
4. Look at Fund Expense Ratios
If you buy ETFs or mutual funds, the brokerage commission is only part of the cost.
Funds generally charge an annual operating expense known as an expense ratio.
For example, suppose you invest $10,000 in an ETF with a 0.10% annual expense ratio.
A simplified estimate of the annual fund expense would be:
$10,000 × 0.10% = $10 per year
If another similar fund charges 0.75%, the simplified cost on the same $10,000 would be:
$10,000 × 0.75% = $75 per year
The difference may appear small in one year, but fees can compound over long investment periods because money paid in fees is no longer invested.
Always compare expense ratios when choosing funds, even if the platform itself charges no trading commission.
5. Compare Account Minimums
For beginners, a high minimum deposit can create an unnecessary obstacle.
Many major online brokerages now allow investors to open standard brokerage accounts without a large minimum deposit.
However, minimums can still apply to:
- Specific mutual funds
- Managed portfolios
- Advisory programs
- Premium account tiers
- Specialized investments
Before opening an account, distinguish between the minimum required to open the brokerage account and the minimum required for a particular investment or service.
6. Fractional Shares Can Help Beginners Start Small
A fractional share allows you to purchase part of a share rather than an entire share.
Imagine a stock trades at $400 per share but you only want to invest $50.
A platform supporting fractional shares may allow you to invest approximately $50 rather than requiring you to buy a full $400 share.
Fractional investing can also make it easier to diversify a smaller portfolio.
For example, a beginner investing $200 might divide the money among several ETFs instead of being limited by the price of whole shares.
Check whether fractional investing applies to:
- Stocks
- ETFs
- Only selected securities
- Automatic recurring purchases
Policies differ between platforms.
7. Evaluate Automatic Investing Features
Consistency is often more useful for a long-term beginner than constantly trying to predict the perfect time to invest.
Automatic investing allows you to schedule recurring transfers and, on some platforms, recurring purchases.
For example, you might arrange:
- $100 every two weeks
- $250 each month
- A contribution every payday
Automation can reduce the temptation to skip contributions when markets feel uncertain.
Before selecting a platform, find out whether recurring investing is available for the investments you want to own.
8. Understand the Main Investment Account Types
Choosing the right account type can be just as important as choosing the platform.
Individual Taxable Brokerage Account
A standard taxable brokerage account provides flexibility. You can generally deposit and withdraw money without the retirement-account restrictions that apply to tax-advantaged accounts.
However, investment income, dividends, interest, and realized capital gains may have tax consequences.
Joint Brokerage Account
A joint account is owned by more than one person.
The legal and tax consequences depend on the form of ownership and applicable law, so understand the account registration before opening one.
Traditional IRA
A Traditional Individual Retirement Account is designed for retirement savings and may provide tax advantages depending on eligibility and circumstances.
Contribution rules, deductions, withdrawals, and tax treatment are governed by federal tax law and can change.
Roth IRA
A Roth IRA is another U.S. retirement account with different tax treatment from a Traditional IRA.
Eligibility, income limits, contribution limits, and withdrawal rules apply.
Beginners should not choose between Roth and Traditional accounts simply based on an app's marketing. The appropriate account depends on individual tax and retirement circumstances.
Custodial Accounts
Some brokerages offer custodial accounts used to hold investments for minors under applicable rules.
Education Savings Accounts
Some investment firms also support education-focused accounts such as 529 plans, though availability and structure vary.
9. Cash Account vs Margin Account
Beginners should pay particular attention to whether they are opening a cash or margin brokerage account.
In a cash account, you generally pay for investments with the money available in your account.
A margin account allows you to borrow money from the brokerage, using securities in the account as collateral.
Margin increases purchasing power, but it also increases risk.
Potential consequences include:
- Interest charges
- Larger losses
- Margin calls
- Forced sale of securities
A beginner who intends to invest only their own savings may prefer to avoid margin until they fully understand how it works.
When opening a brokerage account, verify which account type the application is creating rather than assuming the default is what you want.
10. Compare the Available Investments
Not every platform offers the same investment menu.
A beginner might want access to:
- Broad-market ETFs
- Index mutual funds
- Individual stocks
- Bond funds
- Treasury securities
- Target-date retirement funds
More advanced products such as options, futures, leveraged ETFs, and margin trading are not necessary for building a basic diversified portfolio.
Choose a platform based on investments that match your plan rather than the largest possible product catalog.
11. Consider ETF and Mutual Fund Availability
Many beginners choose ETFs or mutual funds because a single fund can hold dozens, hundreds, or even thousands of securities.
This can make diversification easier than selecting a small number of individual companies.
When evaluating a platform, check:
- How many ETFs are available
- Whether ETF trades are commission-free
- Availability of low-cost index funds
- Mutual fund transaction fees
- Minimum investment requirements
- Automatic investment support
12. Research and Education Matter
Beginners often focus on the appearance of the mobile app and overlook educational resources.
A good investment platform can help users understand concepts before encouraging them to make complicated trades.
Useful educational content may cover:
- Stocks and bonds
- ETFs
- Asset allocation
- Diversification
- Retirement accounts
- Risk
- Taxes
- Market volatility
Research tools may include company financial information, analyst reports, ETF screeners, fund comparisons, news, portfolio analysis, and retirement calculators.
Beginners do not need every professional trading tool, but having reliable educational resources within the platform can reduce dependence on social-media investing advice.
13. Compare Customer Support
When your money is involved, customer service matters.
A beginner may eventually need help with:
- Account verification
- Deposits
- Withdrawals
- Password recovery
- Tax documents
- Beneficiary changes
- Asset transfers
- Trade questions
Compare support methods such as:
- Telephone support
- Live chat
- Physical branches
- 24-hour service
An extremely simple app can become frustrating if receiving assistance is difficult when something goes wrong.
14. Review Security Features
Investment accounts can contain a significant portion of someone's savings, so security should be treated seriously.
Look for features including:
- Two-factor authentication
- Login alerts
- Withdrawal notifications
- Device management
- Strong identity verification
- Fraud monitoring
Also verify that the brokerage is appropriately registered and understand what investor protections apply.
For U.S. brokers, FINRA's BrokerCheck can help investors research brokerage firms and registered professionals.
15. Understand SIPC Protection
Many U.S. brokerage customers may encounter references to Securities Investor Protection Corporation, or SIPC, coverage.
SIPC protection is not the same as bank deposit insurance, and it does not protect investors against ordinary market losses.
If you buy an investment that falls in value, SIPC does not reimburse you simply because your portfolio lost money.
Its role relates primarily to certain missing customer cash and securities if a SIPC-member brokerage firm fails under covered circumstances, subject to applicable limits and rules.
Beginners should understand the difference between protection from brokerage failure and protection from investment risk.
16. Compare Mobile App Quality Without Letting It Drive the Decision
A clean mobile app can make investing easier, but attractive design should not determine where you place your savings.
Evaluate whether the application makes it easy to:
- View your portfolio
- Find cost-basis information
- Review transactions
- Set recurring investments
- Download statements
- Contact support
- Update security settings
Be cautious of platforms that make speculative trading feel like entertainment. Investing involves real financial risk, even when an app makes transactions feel effortless.
17. Watch for Account Transfer and Closing Fees
Beginners frequently focus on what an account costs to open and forget to ask what it costs to leave.
Some brokerages charge fees when you transfer your entire account to another financial institution.
Other potential charges can include:
- Outgoing wire fees
- Paper statement fees
- Returned payment fees
- Broker-assisted transaction fees
- Special handling fees
Review the complete fee schedule before funding an account.
18. Understand Robo-Advisor Fees
If you want automatic portfolio management rather than selecting investments yourself, a robo-advisor can simplify the process.
But automated investing is not necessarily free.
Suppose a robo-advisor charges 0.25% annually on assets under management.
On a $20,000 account, a simplified estimate would be:
$20,000 × 0.25% = $50 annually
If the portfolio grows to $100,000:
$100,000 × 0.25% = $250 annually
The ETFs inside the portfolio may also charge their own expense ratios.
Some automated services instead charge flat monthly subscription fees. A fixed subscription can represent a relatively large percentage of a very small investment account.
For example, a $5 monthly fee equals $60 per year. On a $1,000 portfolio, that alone represents 6% of the starting account value before considering investment performance or fund expenses.
19. Examples of Major Beginner-Oriented Brokerage Platforms
There is no single platform that fits every beginner. The following examples illustrate different features investors may encounter rather than representing a universal ranking.
Fidelity
Fidelity currently advertises no minimum to open its standard brokerage account and $0 online commissions for U.S. stock and ETF trades. It also supports fractional-share investing with small dollar amounts and offers a broad range of stocks, ETFs, mutual funds, bonds, and other products.
Features that may appeal to beginners include educational material, research tools, retirement accounts, fractional shares, and access to customer support.
Investors should still review fees for options, specialized securities, funds, managed services, and other transactions before assuming every service is free.
Charles Schwab
Charles Schwab currently advertises no account minimum for its standard brokerage account and $0 online commissions on listed U.S. stocks and ETFs.
The platform provides educational content, research tools, retirement accounts, fractional-share features for eligible securities, customer support, and access to more advanced trading tools for investors who eventually need them.
Options contracts, broker-assisted transactions, certain fixed-income products, account transfers, and other activities can involve additional charges.
Mobile-First Brokerage Platforms
Mobile-focused brokerages may appeal to beginners because they simplify the process of buying stocks and ETFs.
However, simplicity should be weighed against:
- Available account types
- Retirement options
- Research tools
- Customer support
- Transfer fees
- Cash-management features
- Investment selection
A beginner should not choose an investment platform solely because it makes frequent trading easy.
20. Create a Platform Comparison Table
Before choosing an online broker, build a simple comparison table using information directly from each platform's current fee schedule.
| Feature | Platform A | Platform B | Platform C |
|---|---|---|---|
| Account Minimum | Compare | Compare | Compare |
| Stock Commission | Compare | Compare | Compare |
| ETF Commission | Compare | Compare | Compare |
| Fractional Shares | Yes/No | Yes/No | Yes/No |
| Recurring Investing | Compare | Compare | Compare |
| Traditional IRA | Yes/No | Yes/No | Yes/No |
| Roth IRA | Yes/No | Yes/No | Yes/No |
| Robo-Advisor | Compare | Compare | Compare |
| Account Transfer Fee | Compare | Compare | Compare |
| Customer Support | Compare | Compare | Compare |
This process helps prevent one attractive promotional feature from overshadowing more important differences.
How Much Money Should a Beginner Start With?
There is no universal amount required to begin investing.
Fractional shares and low-minimum brokerage accounts mean that some investors can start with relatively small amounts.
The more important question is whether the money is appropriate to invest.
Before investing, consider whether you have:
- Money for ordinary monthly expenses
- An emergency reserve
- A plan for high-interest debt
- Appropriate insurance
- Enough cash for near-term financial goals
Money needed in the near future may not be suitable for volatile investments such as stocks.
A Simple Beginner Investing Example
Consider a hypothetical investor named Maya.
Maya wants to invest $300 each month for a long-term goal. She does not want to trade frequently or research individual companies every day.
Instead of choosing a platform based on advanced trading features, she compares:
- Account minimum
- ETF commissions
- Fractional-share availability
- Recurring investments
- Index-fund choices
- Retirement accounts
- Fund expense ratios
- Customer support
Her decision is based on the features supporting her long-term plan rather than on which app offers the largest number of trading tools.
This is a useful mindset for beginners: begin with your investment strategy and then choose technology that supports it.
Mistakes Beginners Should Avoid When Choosing an Investment Platform
Choosing Based Only on Free Trades
Trading commission is only one cost. Review fund expenses, advisory fees, transfer charges, margin rates, and other fees.
Opening a Margin Account Without Understanding It
Borrowing to invest can magnify losses. Beginners should understand margin completely before using it.
Choosing an App Because It Encourages Frequent Trading
Easy trading does not mean frequent trading is beneficial. Constant activity can increase mistakes, taxes, and exposure to short-term speculation.
Ignoring Account Type
A taxable brokerage account and a retirement account can have very different tax rules and withdrawal restrictions.
Investing Based on Social Media Hype
A platform should be a tool for executing a financial plan, not a reason to chase whatever stock or investment is currently popular online.
Ignoring Investment Fees
Even if the broker charges no commission, funds inside the account can have ongoing expenses.
Questions to Ask Before Opening an Investment Account
- Is there an account-opening minimum?
- Are stock and ETF trades commission-free?
- What other transaction fees apply?
- Does the platform support fractional shares?
- Can I automate investments?
- Are Traditional and Roth IRAs available?
- What mutual funds and ETFs are available?
- Do funds have transaction fees?
- Does the account charge maintenance fees?
- Are there inactivity fees?
- What is the full account-transfer fee?
- What customer-support options are available?
- Is two-factor authentication supported?
- Does the platform provide research and educational tools?
- Am I opening a cash account or margin account?
- Does the platform offer advisory services?
- How much do those advisory services cost?
- What costs apply to investments inside the account?
Frequently Asked Questions
What is the best investment platform for a complete beginner?
There is no universal best platform. A beginner should compare account minimums, fees, available investments, fractional shares, automated investing, retirement accounts, educational resources, security, and customer service. A simple long-term investor may value different features from someone planning to trade actively.
Can I start investing with $100?
Potentially, yes. Many brokerage accounts have low or no opening minimums, and fractional-share investing may allow small dollar purchases. Whether investing is appropriate depends on your overall financial circumstances and how soon you may need the money.
Are commission-free investment platforms really free?
No investment platform should automatically be considered completely free. A brokerage can charge $0 for certain online stock and ETF trades while other costs still apply, including fund expenses, options fees, advisory charges, margin interest, transfers, and specialized transactions.
Are ETFs good for beginners?
ETFs can provide convenient diversification because a single fund may hold many securities. However, ETFs differ significantly in strategy, risk, diversification, leverage, and expenses. Beginners should understand what an ETF owns before investing.
Should a beginner buy individual stocks or index funds?
The appropriate choice depends on the investor's goals and risk tolerance. Broad diversified index funds can make diversification simpler, while individual stocks require investors to accept company-specific risk and usually require more research.
What is a robo-advisor?
A robo-advisor is an automated investment-management service that typically creates and manages a portfolio based on information such as your goals, timeline, and risk tolerance. Fees and services differ between providers.
Is a Roth IRA an investment?
No. A Roth IRA is a type of retirement account. Investments such as stocks, ETFs, mutual funds, or bonds can be held inside the account, subject to the platform's offerings and applicable rules.
Should a beginner use margin?
Margin involves borrowing money from a brokerage to purchase securities and creates additional risk, including larger losses and potential forced sales. Beginners should understand these risks fully before considering margin borrowing.
Beginner Investment Platform Checklist
Before opening your first account, use this checklist:
- Identify your investment goal.
- Decide whether the money is for retirement or another purpose.
- Choose the appropriate account type.
- Check the minimum deposit.
- Review stock and ETF commissions.
- Read the complete fee schedule.
- Check ETF and mutual fund expense ratios.
- Look for fractional-share support.
- Check recurring investment options.
- Review available index funds and ETFs.
- Compare research and educational resources.
- Check customer-support availability.
- Review security features.
- Confirm whether the account is cash or margin.
- Check transfer and closure fees.
- Read the firm's Form CRS and other disclosures.
- Understand every investment before purchasing it.
Final Thoughts
The best online investment platform for beginners is not necessarily the one with the flashiest mobile app, the largest promotion, or the most trading features.
A good platform should make it easy to follow a sensible investment plan while keeping costs understandable.
Start by determining why you are investing. Then decide which account type fits that goal. Compare brokerage commissions, fund expense ratios, advisory costs, fractional-share features, automatic investing, available securities, customer support, security, and account-transfer fees.
If your objective is long-term investing, prioritize tools that encourage consistent contributions, diversification, cost awareness, and disciplined decision-making rather than constant trading.
Also remember that the platform itself does not determine your investment returns. Your asset allocation, investment choices, fees, behavior, time horizon, and market performance all matter.
Choosing a suitable investment platform is therefore best viewed as building the infrastructure for your financial plan. The platform should make responsible investing easier, not tempt you into taking risks you do not understand.
Take time to read current fee schedules and account disclosures before transferring money. Investment platforms regularly change pricing, features, minimums, and available services, so verify important information directly with the provider before opening or funding an account.
Disclaimer: This article is for general educational and informational purposes only and does not constitute personalized investment, financial, tax, or legal advice. Investing involves risk, including possible loss of principal. Investment products, fees, account requirements, tax rules, and platform features can change. Consider your financial circumstances and, when appropriate, consult a qualified professional before making investment decisions.