Mortgages & Real Estate
Best Mortgage Lenders: How to Compare Rates, Fees, and Loan Terms
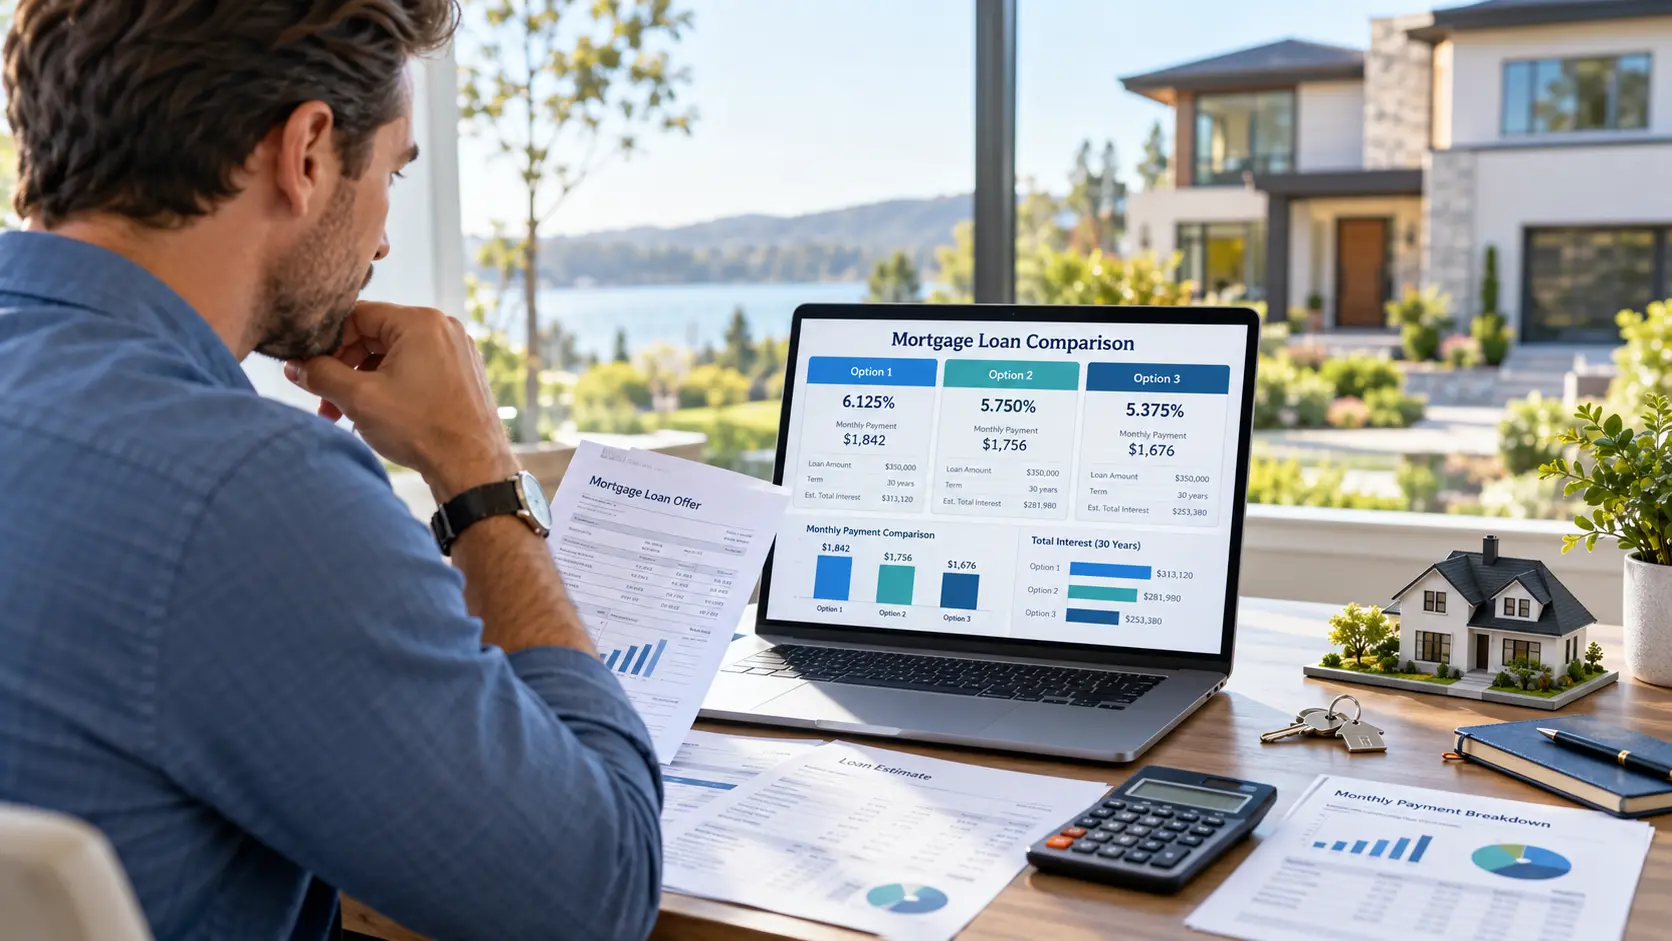
Choosing a mortgage lender is one of the most important financial decisions involved in buying a home. A mortgage can last for 15, 20, or 30 years, and even seemingly small differences in the interest rate, lender fees, loan structure, or closing costs can affect how much you pay over time.
That is why finding the best mortgage lender should involve much more than searching for the lowest advertised mortgage rate.
A lender offering a slightly lower interest rate could charge higher origination fees or require you to buy discount points. Another lender could quote a somewhat higher rate but offer lower closing costs, better customer service, or more favorable loan terms.
The right mortgage therefore depends on your financial situation, down payment, credit profile, loan amount, preferred mortgage type, expected time in the home, and ability to handle both upfront and monthly costs.
This guide explains how to compare mortgage lenders, interest rates, annual percentage rates, fees, discount points, loan terms, monthly payments, and closing costs so you can evaluate mortgage offers more effectively.
What Is a Mortgage Lender?
A mortgage lender is a financial institution or lending company that provides money to borrowers for purchasing or refinancing real estate.
When you obtain a mortgage, you agree to repay the amount borrowed, plus interest and applicable charges, according to the loan agreement. The property generally serves as collateral for the mortgage.
Mortgage lenders can include:
- Traditional banks
- Credit unions
- Mortgage companies
- Online mortgage lenders
- Community banks
- Specialized home-loan lenders
You may also work with a mortgage broker. A broker is different from a lender because the broker generally helps connect borrowers with potential lenders rather than supplying the mortgage funds directly.
What Makes a Mortgage Lender "Best"?
There is no single mortgage lender that is best for every borrower.
A first-time buyer with a small down payment may value different loan programs from a borrower purchasing an expensive property with a large down payment. Likewise, someone planning to stay in a house for 20 years may evaluate discount points differently from someone expecting to move again within several years.
A strong mortgage offer generally combines several important features:
- Competitive interest rate
- Reasonable APR
- Manageable lender fees
- Appropriate loan term
- Affordable monthly payment
- Reasonable closing costs
- Clear mortgage insurance requirements
- Suitable fixed or adjustable rate structure
- Transparent loan documentation
- Reliable closing process
- Responsive customer service
Rather than asking only, "Who has the lowest rate?" ask, "Which mortgage provides the best combination of cost, terms, affordability, and service for my situation?"
1. Compare Mortgage Interest Rates
The mortgage interest rate is one of the most visible parts of a home loan. It represents the percentage charged for borrowing the mortgage principal.
A lower rate can reduce your monthly principal-and-interest payment and potentially reduce the total interest paid over the life of the loan.
However, comparing rates requires care.
Imagine two lenders offering the same loan amount:
| Feature | Lender A | Lender B |
|---|---|---|
| Loan Amount | $350,000 | $350,000 |
| Interest Rate | 6.25% | 6.50% |
| Discount Points | $7,000 | $0 |
| Term | 30 Years | 30 Years |
Lender A appears cheaper if you look only at the interest rate. But the borrower must pay $7,000 upfront to obtain that rate.
Whether that is worthwhile depends partly on how long the borrower expects to keep the mortgage.
This is why mortgage rates should never be compared without also comparing points and lender fees.
2. Compare APR, Not Just the Advertised Rate
The annual percentage rate, or APR, provides another way to evaluate borrowing costs.
The mortgage interest rate reflects the cost of borrowing the principal, while APR is a broader measure that incorporates the interest rate and certain additional loan charges.
These may include items such as:
- Discount points
- Mortgage broker fees
- Certain lender charges
- Other qualifying loan costs
For that reason, APR is usually higher than the stated mortgage interest rate.
Consider this simplified example:
| Offer | Interest Rate | APR |
|---|---|---|
| Mortgage A | 6.25% | 6.62% |
| Mortgage B | 6.35% | 6.49% |
Mortgage A has the lower interest rate but the higher APR. That could indicate that the first mortgage includes more upfront financing charges.
APR is useful, but it should not be the only number you consider. This is especially important when comparing fixed-rate and adjustable-rate mortgages because their future rates can behave differently.
3. Request Loan Estimates From Multiple Lenders
One of the most useful ways to compare mortgage lenders is to obtain formal Loan Estimates for comparable loans.
In the United States, a Loan Estimate is a standardized three-page document that provides important information about a mortgage offer, including the estimated interest rate, payment, closing costs, and other loan features.
The Consumer Financial Protection Bureau recommends requesting Loan Estimates from at least three lenders when shopping for a mortgage.
You can learn more about comparing mortgage offers through the Consumer Financial Protection Bureau's mortgage comparison guidance.
When comparing Loan Estimates, make sure the offers are based on similar assumptions, including:
- Same home price
- Same loan amount
- Same down payment
- Same loan type
- Same loan term
- Similar rate-lock timing
- Same amount of discount points, where possible
Otherwise, you may accidentally compare two different mortgage structures rather than two competing prices for a similar mortgage.
4. Understand Mortgage Origination Charges
Mortgage lenders can charge upfront fees for originating and processing a loan.
These may appear under different names, including:
- Origination fee
- Application fee
- Underwriting fee
- Processing fee
- Administrative fee
- Verification fee
- Rate-lock fee
One lender may combine several services into one origination charge, while another may list each separately.
Do not get distracted by the number of fee lines. What matters most when comparing similar offers is the total amount of lender-controlled charges.
Example
| Fees | Lender A | Lender B |
|---|---|---|
| Origination | $1,500 | $900 |
| Underwriting | $750 | $0 |
| Processing | $450 | $250 |
| Total | $2,700 | $1,150 |
Even if both lenders advertise similar rates, Lender B is charging $1,550 less in this simplified example.
5. Understand Discount Points
Discount points allow borrowers to pay additional money at closing in exchange for a lower mortgage interest rate.
One mortgage point generally equals 1% of the loan amount.
For example, on a $400,000 mortgage:
1 point = $4,000
Paying points can potentially make sense when the interest savings over the time you keep the mortgage exceed the upfront cost.
Break-Even Example
Suppose paying $4,000 in points reduces your mortgage payment by $60 per month.
The approximate break-even period would be:
$4,000 ÷ $60 = approximately 67 months
That is about five years and seven months.
If you sell the home or refinance after two years, you may not have kept the lower rate long enough to recover the upfront cost.
If you keep the mortgage for significantly longer than the break-even period, paying points could potentially provide greater value.
The calculation should always use the actual mortgage offers you receive.
6. Understand Lender Credits
Lender credits work in roughly the opposite direction from discount points.
Instead of paying additional money upfront to receive a lower rate, you may accept a higher interest rate in exchange for the lender contributing toward some of your closing costs.
This may appeal to borrowers who want to reduce the amount of cash required at closing.
However, reducing today's closing costs can result in a higher monthly payment and potentially greater interest expense if the loan remains outstanding for a long period.
When comparing lender credits, ask each lender to show you:
- The interest rate without credits
- The interest rate with credits
- The exact dollar amount of the credit
- The resulting monthly payment
- The difference in costs over several potential time periods
7. Compare 15-Year and 30-Year Mortgages
The mortgage term affects both your monthly payment and total borrowing cost.
Two common fixed-rate mortgage terms are 15 years and 30 years.
| Feature | 15-Year Mortgage | 30-Year Mortgage |
|---|---|---|
| Monthly Principal and Interest | Usually higher | Usually lower |
| Debt Payoff | Faster | Slower |
| Total Interest | Generally lower | Generally higher |
| Monthly Budget Flexibility | Lower | Higher |
A shorter mortgage term can reduce total interest substantially, but the larger monthly payment can put more pressure on your budget.
Do not choose a 15-year mortgage simply because it saves interest if the required payment would leave you with little room for emergencies, retirement contributions, insurance, property maintenance, or other important expenses.
8. Compare Fixed-Rate and Adjustable-Rate Mortgages
A fixed-rate mortgage generally keeps the same interest rate for the agreed loan term.
This provides predictable principal-and-interest payments.
An adjustable-rate mortgage, commonly called an ARM, has an interest rate that can change according to the terms of the loan after an initial period.
An ARM may begin with a lower rate than a comparable fixed-rate mortgage, but the future rate could rise.
If you are considering an ARM, understand:
- How long the initial rate lasts
- When the first adjustment can occur
- How frequently the rate adjusts
- Which index is used
- The lender's margin
- Periodic adjustment caps
- Lifetime rate cap
- Potential maximum payment
Do not select an ARM based solely on the introductory payment. Ask what your payment could become if the rate increases.
9. Consider the Down Payment Requirement
Your down payment affects the amount you borrow and can influence the mortgage programs available to you.
A larger down payment generally reduces the loan principal.
For example:
| Home Price | Down Payment | Mortgage Amount |
|---|---|---|
| $400,000 | $20,000 | $380,000 |
| $400,000 | $40,000 | $360,000 |
| $400,000 | $80,000 | $320,000 |
A lower loan amount generally means lower principal-and-interest payments, assuming the other loan terms remain equal.
However, using nearly all your available savings for a large down payment may leave you without enough money for closing costs, repairs, moving expenses, or emergencies.
Consider the entire financial picture rather than maximizing the down payment automatically.
10. Understand Mortgage Insurance
Depending on the mortgage program and your down payment, mortgage insurance may be required.
Mortgage insurance generally protects the lender or mortgage investor against certain losses if the borrower fails to repay the loan. It does not function like homeowners insurance, which protects against specified losses involving the home and property.
When comparing mortgage offers, ask:
- Is mortgage insurance required?
- What is the initial cost?
- What is the monthly cost?
- Can the mortgage insurance eventually be removed?
- If so, under what conditions?
- Does the cost change over time?
Mortgage insurance can materially affect the total monthly housing payment, so do not compare lenders using principal and interest alone.
11. Calculate Your True Monthly Housing Payment
Your mortgage payment may include more than principal and interest.
Depending on the loan and escrow arrangement, your monthly housing expense can include:
- Principal
- Interest
- Property taxes
- Homeowners insurance
- Mortgage insurance
- Homeowners association fees paid separately, where applicable
Suppose your principal-and-interest payment is $2,000 per month.
Your complete monthly housing costs might look more like:
| Cost | Monthly Amount |
|---|---|
| Principal and Interest | $2,000 |
| Property Taxes | $450 |
| Homeowners Insurance | $150 |
| Mortgage Insurance | $125 |
| HOA Fee | $175 |
| Total | $2,900 |
Buying based on the $2,000 figure while ignoring another $900 of housing expenses could result in a budget that is much tighter than expected.
12. Compare Closing Costs
Closing costs are the expenses associated with completing the mortgage and real estate transaction.
They can include:
- Lender origination charges
- Appraisal fees
- Credit-related fees
- Title services
- Title insurance
- Recording charges
- Government fees
- Prepaid interest
- Initial escrow deposits
- Taxes
- Homeowners insurance premiums
Not every closing cost is controlled by the mortgage lender.
Property taxes, for example, do not become cheaper simply because one lender's Loan Estimate initially shows a lower estimate.
When comparing lenders, pay particular attention to the costs the lender can control, such as origination charges, required lender-selected services, points, and lender credits.
13. Be Careful With "No Closing Cost" Mortgages
A mortgage advertised as having "no closing costs" does not necessarily mean the costs have disappeared.
The lender may:
- Provide a lender credit in exchange for a higher interest rate
- Finance certain costs into the loan where permitted
- Structure the loan so the borrower pays more over time
This can still be useful for some borrowers, particularly when preserving upfront cash is a priority.
But compare the higher payment or loan balance against the amount being saved at closing.
The key question is not whether closing costs are paid today. The question is how the financing structure affects your total cost during the period you expect to keep the mortgage.
14. Compare the Five-Year Cost of Borrowing
One useful method for comparing mortgage offers is to look beyond the first month's payment and estimate the cost over several years.
The standardized Loan Estimate includes a comparison section that can help borrowers understand costs over the first five years.
When evaluating similar fixed-rate mortgage offers, consider:
- Total payments over five years
- Principal paid down during that period
- Interest paid
- Upfront lender costs
- Points
- Potential lender credits
This can be more useful than comparing rates alone, especially if you think you may move or refinance within several years.
15. Evaluate the Lender's Ability to Close on Time
Price matters, but mortgage execution matters too.
A low-cost mortgage offer may be less attractive if the lender repeatedly misses deadlines, cannot complete underwriting, or struggles to coordinate the closing.
When evaluating mortgage lenders, ask:
- What is the typical closing timeline?
- How quickly can underwriting begin?
- How are documents uploaded?
- Who will be my primary contact?
- How quickly are questions answered?
- Can I track the application online?
- How does the lender handle appraisal delays?
- What happens if the closing date changes?
If you are purchasing a home under contract, a missed financing deadline can create complications beyond the mortgage itself.
16. Understand the Mortgage Rate Lock
Mortgage rates can change while you are purchasing a home.
A rate lock can protect an agreed rate for a specified period, subject to the lender's terms and any required conditions.
Before locking, ask:
- How long does the lock last?
- Is there a fee?
- What happens if closing is delayed?
- How much does a lock extension cost?
- Can the rate decrease if market rates fall?
- What conditions could invalidate the lock?
When comparing lenders, make sure quoted rates represent similar lock periods. A quote based on a very short lock should not automatically be considered cheaper than a quote designed to remain valid through your expected closing date.
17. Consider the Mortgage Loan Type
The best lender may depend partly on the type of mortgage you need.
Common categories include:
Conventional Mortgages
Conventional mortgages are not insured or guaranteed by a federal government agency. Eligibility and pricing depend on the specific program, lender, credit profile, down payment, and other underwriting considerations.
FHA Loans
Federal Housing Administration-insured mortgages can provide another option for eligible borrowers, including some buyers with lower down payments or credit profiles that may make conventional financing more difficult.
VA Loans
Eligible veterans, service members, and certain surviving spouses may qualify for mortgages backed by the Department of Veterans Affairs.
USDA Loans
Eligible borrowers purchasing qualifying properties in designated areas may have access to USDA-supported mortgage programs.
Jumbo Mortgages
Borrowers purchasing higher-priced properties may require jumbo financing when the loan exceeds applicable conforming loan limits.
A lender that is highly competitive for conventional mortgages may not offer the strongest terms for VA, FHA, USDA, or jumbo borrowers. Compare lenders that have meaningful experience with the program you intend to use.
18. Check Prepayment and Risky Loan Features
Most borrowers expect a mortgage to work in a straightforward way: make payments, reduce the balance, and eventually own the home free of the mortgage.
However, you should still review the documents for unusual or potentially costly features.
Look for:
- Prepayment penalties
- Balloon payments
- Interest-only periods
- Negative amortization
- Adjustable rates
- Large future payment changes
If you do not understand a feature, ask for a written explanation before agreeing to the mortgage.
How Your Credit Score Affects Mortgage Offers
Your credit profile is one of several factors lenders may use when determining eligibility and pricing.
Generally, a stronger credit profile can help a borrower qualify for more competitive financing, although mortgage pricing also depends on factors such as:
- Loan amount
- Down payment
- Loan-to-value ratio
- Property type
- Loan program
- Debt-to-income ratio
- Occupancy
- Market conditions
- Points and lender credits
If you are planning a home purchase months in advance, reviewing your credit reports and addressing genuine inaccuracies before applying can give you more time to prepare.
How to Compare Three Mortgage Offers
A simple worksheet can help you evaluate lenders side by side.
| Mortgage Feature | Lender A | Lender B | Lender C |
|---|---|---|---|
| Loan Amount | $400,000 | $400,000 | $400,000 |
| Loan Term | 30 Years | 30 Years | 30 Years |
| Rate Type | Fixed | Fixed | Fixed |
| Interest Rate | Compare Quote | Compare Quote | Compare Quote |
| APR | Compare | Compare | Compare |
| Points | Compare | Compare | Compare |
| Origination Charges | Compare | Compare | Compare |
| Lender Credits | Compare | Compare | Compare |
| Monthly P&I | Compare | Compare | Compare |
| Cash to Close | Compare | Compare | Compare |
| Rate Lock | Compare | Compare | Compare |
Using the same loan scenario for all three lenders is essential. Otherwise, a lender may appear cheaper only because its quote uses a different down payment, points structure, or loan term.
Questions to Ask a Mortgage Lender
Before choosing a lender, ask questions such as:
- What interest rate are you offering?
- Is the rate fixed or adjustable?
- What is the APR?
- Does the quoted rate require discount points?
- What are your total origination charges?
- Are lender credits included?
- What is the estimated monthly principal-and-interest payment?
- Is mortgage insurance required?
- What are the estimated total closing costs?
- How much cash will I need at closing?
- How long is the rate lock?
- Does extending the rate lock cost extra?
- Are there prepayment penalties?
- How long do you expect the loan to take to close?
- Who will manage my application?
- What documents will I need?
- Can you show me an alternative offer with zero points?
- Can you show me an option using lender credits?
Mortgage Lender Red Flags
Home buyers should also watch for warning signs.
Be cautious if a lender:
- Refuses to clearly explain fees
- Pressures you to sign immediately
- Promises guaranteed approval before reviewing your finances
- Encourages you to provide false information
- Changes important terms without explanation
- Quotes a rate without explaining points
- Avoids discussing closing costs
- Provides numbers that are dramatically different from written documents
- Cannot explain an adjustable-rate structure
- Uses confusing language to prevent comparison
Your written mortgage documents matter more than verbal promises.
Should You Use a Mortgage Broker?
A mortgage broker can help borrowers search among multiple lenders and loan programs.
This can be useful if your financial situation is unusual or if you want assistance navigating numerous mortgage options.
However, understand how the broker is compensated.
Ask:
- Which lenders does the broker work with?
- How is the broker paid?
- Are broker costs reflected in the loan?
- Does the broker compare the entire market or only selected lenders?
- What fees will you personally pay?
You can also compare a broker's offer with direct quotes from banks, credit unions, and mortgage lenders.
Can You Negotiate a Mortgage?
Mortgage offers are not necessarily take-it-or-leave-it proposals.
After receiving several Loan Estimates, you may be able to ask lenders whether they can improve their offers.
Areas that may potentially differ between lenders include:
- Interest rate
- Origination charges
- Points
- Lender credits
- Certain lender-controlled fees
A competing written Loan Estimate can be particularly useful during this conversation.
If one lender offers strong service but another offers lower lender-controlled costs, you can ask the preferred lender whether it can match or improve the competing terms.
Just make sure a reduction in one cost is not being offset by an increase somewhere else.
How Much Mortgage Can You Really Afford?
The amount a lender approves and the amount that comfortably fits your household budget are not necessarily the same.
Your personal affordability calculation should consider:
- Mortgage payment
- Property taxes
- Homeowners insurance
- Mortgage insurance
- HOA fees
- Utilities
- Maintenance
- Repairs
- Transportation
- Other debts
- Retirement savings
- Emergency savings
- Childcare and family expenses
Owning a home creates expenses beyond the mortgage itself. A payment that looks affordable during underwriting may feel much less comfortable after utilities, repairs, taxes, insurance, and other household costs are included.
Frequently Asked Questions
How many mortgage lenders should I compare?
Comparing at least three mortgage offers is a useful starting point. More comparisons may provide additional information, but focus on comparable Loan Estimates issued for similar loan amounts, terms, points, and rate-lock periods.
Is the lender with the lowest mortgage rate always best?
No. A low rate may require expensive discount points or come with higher lender fees. Compare the APR, origination charges, points, monthly payment, cash to close, and expected borrowing cost.
What is the difference between mortgage rate and APR?
The interest rate reflects the cost of borrowing the principal, while APR incorporates the interest rate plus certain additional loan costs. APR can therefore help you evaluate the broader cost of financing, although it should not be used in isolation.
What are mortgage points?
Mortgage discount points are upfront charges paid in exchange for a lower interest rate. One point generally equals 1% of the mortgage amount. Whether points make financial sense depends partly on how long you expect to keep the loan.
Can I negotiate mortgage lender fees?
Some lender-controlled charges may be negotiable. Having competing Loan Estimates can give you useful information when asking a lender to improve its offer.
Is a 15-year mortgage better than a 30-year mortgage?
Neither term is universally better. A 15-year loan usually requires larger monthly payments but can reduce total interest and repay the mortgage faster. A 30-year mortgage generally offers lower required monthly payments but can cost more in interest over a longer repayment period.
Should I choose a fixed-rate or adjustable-rate mortgage?
A fixed-rate mortgage provides greater payment predictability for principal and interest. An adjustable-rate mortgage can offer a different initial pricing structure but exposes the borrower to potential future rate changes. Compare the initial rate, adjustment schedule, caps, and potential maximum payment.
What does cash to close mean?
Cash to close is the amount of money you are expected to bring to the mortgage closing after accounting for items such as the down payment, closing costs, deposits, credits, and other transaction adjustments.
Does getting mortgage quotes hurt my credit?
Mortgage applications can involve credit inquiries. Credit-scoring models may provide special treatment for certain multiple mortgage inquiries made within a shopping period, but the exact treatment varies by scoring model. Rather than avoiding comparison shopping solely because of inquiries, organize your mortgage shopping efficiently and ask prospective lenders how and when they will pull your credit.
Mortgage Comparison Checklist
Before choosing your mortgage lender, review this final checklist:
- Compare multiple lenders.
- Request comparable Loan Estimates.
- Check the interest rate.
- Compare APR.
- Identify discount points.
- Review lender credits.
- Compare origination charges.
- Review the mortgage term.
- Confirm whether the rate is fixed or adjustable.
- Calculate principal and interest.
- Add taxes and insurance.
- Include mortgage insurance where applicable.
- Review total closing costs.
- Check cash to close.
- Review the rate-lock period.
- Look for prepayment penalties or unusual loan features.
- Consider how long you expect to keep the mortgage.
- Confirm the lender can meet your closing schedule.
- Ask whether lender-controlled costs can be negotiated.
- Read the final documents carefully before signing.
Final Thoughts
Finding the best mortgage lender is ultimately an exercise in comparison, not simply a search for the lowest advertised interest rate.
Start by deciding what type of mortgage and loan term fit your financial situation. Then request comparable offers from multiple lenders and evaluate each one using the same criteria.
Look at the interest rate, APR, points, origination charges, lender credits, monthly payment, closing costs, mortgage insurance, cash to close, and loan term. If you are considering an adjustable-rate mortgage, understand exactly when the rate can change and how high the payment could potentially become.
Also consider how long you expect to keep the mortgage. Paying additional money upfront for discount points may be difficult to justify if you expect to refinance or move before reaching the break-even point. Conversely, accepting a higher interest rate for lender credits can reduce your upfront costs but increase your longer-term borrowing expense.
Finally, remember that a mortgage must work within your entire household budget. The maximum amount a lender is willing to approve is not necessarily the amount you should borrow.
A careful mortgage comparison can help you understand exactly what you are paying, avoid expensive surprises, and choose financing that remains manageable long after you receive the keys to your home.
Disclaimer: This article is for general educational and informational purposes only and does not constitute financial, legal, tax, or mortgage advice. Mortgage rates, fees, lending requirements, government programs, and loan terms can change. Always review current loan documents and lender disclosures and consider seeking advice from an appropriately qualified professional before making a major borrowing decision.