Small Business
Best Small Business Insurance: Coverage Types, Costs & How to Choose
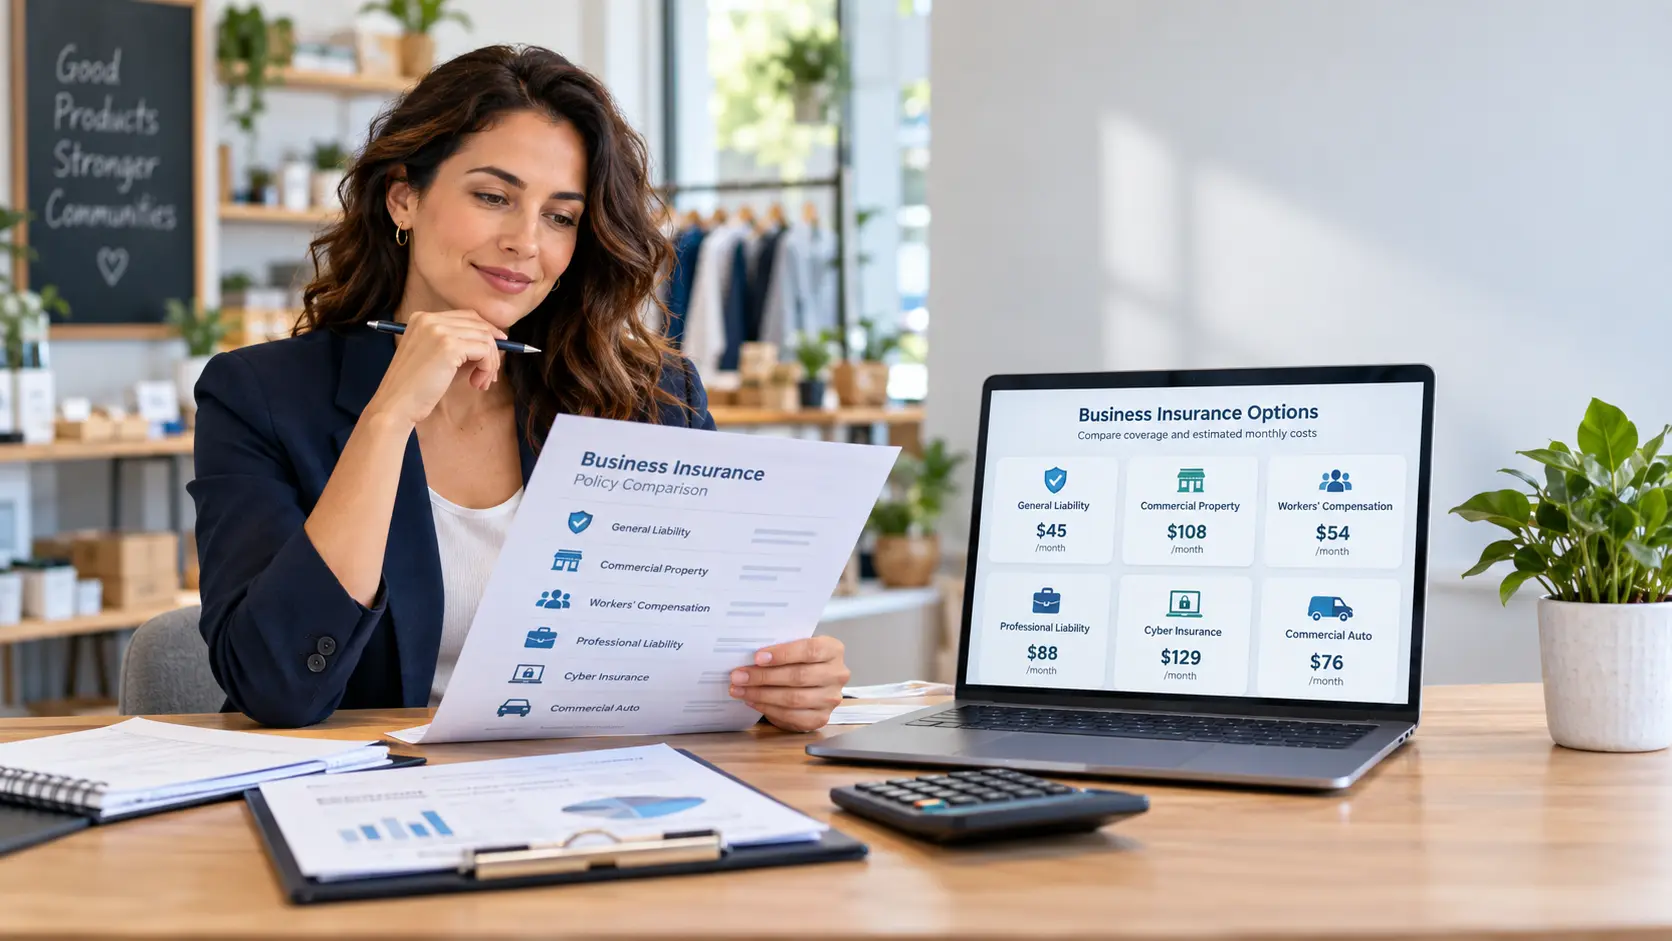
Running a small business involves risk. A customer could slip inside your store, an employee could be injured at work, expensive equipment could be damaged in a fire, a professional mistake could lead to a lawsuit, or a cyberattack could disrupt your operations and expose sensitive information.
Small business insurance is designed to transfer some of those financial risks to an insurer. Instead of your company having to absorb the entire cost of a covered lawsuit, accident, property loss, or other event, an insurance policy may pay eligible expenses according to its limits, deductibles, exclusions, and other terms.
The challenge is deciding which policies your business actually needs.
A freelance graphic designer working from home does not face the same risks as a construction contractor with 15 employees. A retail store needs different protection from a software consulting company. A restaurant may need property, liability, workers' compensation, commercial auto, equipment breakdown, and other coverage that a one-person online business may not require.
This guide explains the major types of small business insurance, typical costs, coverage limits, deductibles, exclusions, and practical steps for comparing policies so you can make a more informed decision.
What Is Small Business Insurance?
Small business insurance is a broad term covering commercial insurance policies designed to protect companies against particular financial risks.
Rather than purchasing one universal policy that covers every possible problem, businesses typically combine several types of coverage based on their operations.
Common policies include:
- General liability insurance
- Commercial property insurance
- Business owner's policy
- Professional liability insurance
- Workers' compensation insurance
- Commercial auto insurance
- Cyber liability insurance
- Product liability insurance
- Business interruption insurance
- Employment practices liability insurance
- Commercial umbrella insurance
The best insurance package is therefore not necessarily the one with the most policies. It is the combination that addresses the meaningful risks your particular business faces without paying unnecessarily for overlapping or irrelevant coverage.
Why Small Businesses Need Insurance
Many small companies have limited cash reserves. A major lawsuit, property loss, accident, or prolonged interruption could create expenses large enough to threaten the survival of the business.
Insurance can help protect against financial losses that would be difficult for the company to absorb independently.
Insurance may also be required by:
- State law
- Local regulations
- A commercial landlord
- A lender
- A client contract
- A professional licensing authority
- A business partner
For example, workers' compensation requirements depend heavily on where a business operates and how many people it employs. Commercial leases also commonly require tenants to carry certain liability limits.
Insurance should therefore be considered both a risk-management decision and a potential legal or contractual requirement.
1. General Liability Insurance
General liability insurance is one of the most common policies purchased by small businesses.
It is designed primarily to protect a business against certain third-party claims involving bodily injury, property damage, and some personal or advertising injuries.
Example
Suppose a customer enters your retail store, slips on a wet floor, suffers an injury, and alleges that your business was negligent.
A covered general liability policy may help pay eligible costs such as:
- Legal defense expenses
- Medical expenses
- Settlements
- Court judgments, subject to policy terms
General liability can also help in situations where your business accidentally damages someone else's property.
What General Liability Usually Does Not Cover
General liability is broad, but it is not universal protection.
It generally does not replace specialized policies for:
- Employee workplace injuries
- Professional errors
- Commercial vehicle accidents
- Intentional wrongdoing
- Many cyber incidents
- Damage to your own business property
Review exclusions carefully rather than assuming the words "general liability" mean every type of liability is covered.
2. Business Owner's Policy
A business owner's policy, commonly called a BOP, combines several important types of coverage in one package.
A typical BOP may combine:
- General liability insurance
- Commercial property coverage
- Business interruption or business income coverage
For eligible small businesses, bundling these coverages can sometimes cost less than purchasing comparable policies separately.
A BOP can be particularly attractive for small offices, professional firms, retailers, restaurants, and certain other relatively small or lower-risk operations.
However, not every company qualifies, and a standard BOP normally does not automatically provide every kind of insurance a business might need.
For example, you may still require separate:
- Workers' compensation
- Commercial auto insurance
- Professional liability
- Cyber coverage
- Employment practices liability
Always examine the actual policy rather than assuming every BOP contains identical protection.
3. Commercial Property Insurance
Commercial property insurance protects eligible business property against covered causes of loss.
Depending on the policy, protected property might include:
- Buildings owned by the business
- Furniture
- Computers
- Machinery
- Equipment
- Inventory
- Tools
- Fixtures
Imagine a fire damages your office and destroys computers, desks, inventory, and equipment. Without appropriate property coverage, replacing those assets could require a large amount of business cash.
Property policies have limits and exclusions, and not every event is automatically covered. Floods and earthquakes, for example, may require separate or specialized coverage depending on the location and policy.
4. Business Interruption Insurance
Property damage can create two financial problems.
First, you may need to repair or replace damaged property. Second, your business may be unable to operate while repairs are being completed.
Business interruption insurance, also called business income insurance, may help replace certain lost income and cover eligible continuing expenses when operations are suspended because of a covered event.
Depending on the policy and circumstances, covered expenses may include:
- Lost business income
- Rent
- Some payroll expenses
- Temporary location costs
- Certain ongoing operating expenses
The National Association of Insurance Commissioners explains that business interruption insurance commonly appears as part of a business owner's policy and is generally triggered by covered physical property damage.
It is important to review waiting periods, coverage periods, limits, and the events that qualify for business income coverage.
5. Professional Liability Insurance
Professional liability insurance is particularly important for businesses that provide advice or professional services.
It is also commonly called errors and omissions insurance, or E&O.
Potential users include:
- Consultants
- Accountants
- Technology professionals
- Marketing agencies
- Designers
- Real estate professionals
- Financial professionals
- Other service providers
Professional liability is designed to address certain claims arising from professional mistakes, negligence, errors, omissions, or failure to perform services according to expected standards.
Example
Suppose a consultant makes an error that allegedly causes a client significant financial loss. General liability coverage may not address the claim because the loss arose from professional services rather than a customer physically injuring themselves on the business premises.
Professional liability coverage may be the more relevant policy in that situation, subject to its terms.
6. Workers' Compensation Insurance
Businesses with employees need to pay particular attention to workers' compensation requirements.
Workers' compensation generally provides benefits when an eligible employee suffers a job-related injury or illness.
Benefits can include:
- Medical treatment
- Rehabilitation
- A portion of lost wages
- Certain disability benefits
- Death benefits in eligible cases
Requirements vary by jurisdiction.
In the United States, workers' compensation is mandatory for most employers in most states, although employee thresholds, exemptions, industries, and specific requirements differ. Businesses should verify current requirements directly with the appropriate state authority or licensed insurance professional.
Do not assume that a very small business is automatically exempt.
7. Commercial Auto Insurance
If your business owns or uses vehicles, personal auto insurance may not provide appropriate protection for commercial activities.
Commercial auto insurance can cover eligible vehicles used in business operations.
Examples include:
- Delivery vans
- Service vehicles
- Company cars
- Construction trucks
- Food delivery vehicles
- Vehicles transporting equipment
Coverage can include liability for injuries and property damage and, depending on the policy, physical damage to the insured vehicle.
If employees use personal vehicles for business purposes, ask about hired and non-owned auto coverage as well.
8. Cyber Liability Insurance
Cybersecurity is no longer only a concern for large technology companies.
A small retailer, accounting firm, medical office, online store, marketing agency, or professional services company may collect valuable information including:
- Customer names
- Email addresses
- Payment information
- Employee records
- Confidential business data
A data breach, ransomware attack, phishing incident, or other cyber event can result in substantial recovery expenses.
Cyber insurance may provide coverage for certain costs such as:
- Data breach response
- Customer notification
- Credit monitoring
- Cyber incident investigation
- Data restoration
- Legal expenses
- Business interruption from covered cyber incidents
- Certain third-party liability claims
Cyber policies can differ significantly. Review requirements involving security controls, backups, multifactor authentication, exclusions, ransomware, and social-engineering losses.
9. Product Liability Insurance
Businesses that manufacture, distribute, wholesale, or sell physical products can face claims alleging that a product caused injury or property damage.
Product liability coverage may help address eligible claims involving issues such as:
- Manufacturing defects
- Design defects
- Inadequate warnings
- Product-related injuries
Product exposure can vary dramatically between industries.
A company selling low-risk office supplies presents a different risk profile from a business manufacturing children's products, electrical equipment, food, or machinery.
If products represent a significant part of your operations, make sure your liability policy is structured for that exposure.
10. Employment Practices Liability Insurance
Companies with employees may also consider employment practices liability insurance, commonly abbreviated EPLI.
This coverage can address certain employment-related claims such as allegations involving:
- Wrongful termination
- Discrimination
- Harassment
- Failure to promote
- Other covered employment practices
General liability insurance normally does not replace employment practices liability coverage.
As your workforce grows, employment-related exposure can become increasingly important.
11. Commercial Umbrella Insurance
Commercial umbrella insurance can provide additional liability limits above certain underlying insurance policies.
For example, imagine your underlying liability policy has a $1 million limit and your business suffers a covered liability loss that exceeds that amount.
An appropriate umbrella policy may provide additional protection above the underlying limit, subject to policy terms.
Businesses with substantial assets, significant public exposure, large contracts, or potentially severe liability risks may want to discuss higher liability limits with an insurance professional.
12. Home-Based Business Insurance
A common mistake among home-based entrepreneurs is assuming homeowners or renters insurance fully covers business activities.
Personal insurance may provide limited or no protection for certain business property and liability claims.
If you operate from home, consider your exposure to:
- Business computers and equipment
- Inventory stored at home
- Customer visits
- Business deliveries
- Professional liability
- Cyber incidents
- Loss of business income
Depending on the business, an endorsement, in-home business policy, BOP, professional liability policy, or other commercial insurance may be appropriate.
How Much Does Small Business Insurance Cost?
There is no standard price for small business insurance because insurers calculate premiums according to the risks presented by a particular business.
Recent published insurance marketplace data provides useful examples, but these figures should not be treated as guaranteed quotes.
| Coverage Type | Example Median Monthly Cost |
|---|---|
| General Liability | About $45 |
| Business Owner's Policy | About $83 |
| Professional Liability | About $88 |
| Workers' Compensation | About $54 |
| Commercial Property | About $108 |
| Cyber Insurance | About $129 |
These amounts are examples based on a specific population of small businesses purchasing coverage and should not be assumed to represent what your company will pay.
A low-risk independent consultant working from home could pay very differently from a roofing contractor, restaurant, medical practice, or manufacturer.
What Determines Business Insurance Cost?
Insurers consider many factors when calculating premiums.
Industry
The type of work you perform can have a major effect on cost.
A bookkeeping firm generally has different physical injury exposure than a construction company.
Business Location
Insurance costs can vary by state, city, crime rates, weather risks, court environment, and local regulations.
Number of Employees
More employees can create additional exposure, particularly for workers' compensation and employment practices claims.
Payroll
Workers' compensation premiums frequently depend partly on payroll and employee job classifications.
Annual Revenue
Higher revenue can sometimes indicate greater customer activity or exposure, depending on the policy.
Claims History
A history of frequent or severe insurance claims can result in higher premiums.
Coverage Limits
Higher limits generally provide greater potential insurance protection but can increase premiums.
Deductible
A higher deductible can sometimes reduce the premium because the business retains more of the initial loss.
However, the deductible should remain affordable if a claim occurs.
Property Value
A company with expensive machinery, inventory, furniture, and technology may require higher property limits.
Security and Risk Controls
Insurers may consider factors such as:
- Fire protection
- Employee safety programs
- Cybersecurity practices
- Alarm systems
- Building condition
- Driver history
- Claims prevention procedures
Understanding Policy Limits
A policy limit is the maximum amount an insurer will pay under specified circumstances according to the policy.
General liability policies commonly distinguish between a per-occurrence limit and an aggregate limit.
Per-Occurrence Limit
This generally represents the maximum available for a single covered occurrence, subject to the contract.
Aggregate Limit
This generally represents the maximum the insurer will pay for covered losses during the applicable policy period under that aggregate.
For example, a policy might show:
- $1 million per occurrence
- $2 million general aggregate
This does not mean every possible event is covered for $1 million. Coverage still depends on definitions, exclusions, endorsements, sublimits, deductibles, and the specific circumstances of the claim.
Understanding Deductibles
A deductible is the portion of a covered loss that the policyholder is responsible for paying according to the policy terms.
Suppose covered property damage totals $20,000 and the applicable deductible is $2,500.
In a simplified example, the insurer may calculate the covered payment after accounting for that deductible and any other policy conditions.
Higher deductibles can reduce insurance premiums in some situations, but selecting an excessively high deductible simply to save money can create a cash-flow problem after a loss.
Choose a deductible your business could realistically afford.
Claims-Made vs Occurrence Coverage
Business owners purchasing professional liability or certain other liability policies may encounter the terms "claims-made" and "occurrence."
The distinction is important.
An occurrence policy generally responds based on when the covered incident occurred, subject to the policy terms.
A claims-made policy generally depends on when the claim is made and reported and whether the event occurred after any applicable retroactive date.
If you cancel or switch claims-made insurance, you may need to consider prior-acts coverage or an extended reporting period.
Do not cancel a professional liability policy without understanding how the change could affect protection for previous work.
How to Choose the Right Small Business Insurance
A useful approach is to begin with risks rather than policies.
Step 1: List Your Major Risks
Ask what could realistically create a serious financial loss.
Examples include:
- Customer injuries
- Property damage
- Professional mistakes
- Employee injuries
- Cyberattacks
- Vehicle accidents
- Product liability
- Fire or theft
- Business interruption
- Employee lawsuits
Step 2: Identify Required Insurance
Check legal requirements, commercial leases, client contracts, loan agreements, and professional licensing requirements.
Required insurance should be addressed before optional coverage is evaluated.
Step 3: Estimate Potential Losses
Consider what would happen financially if an uninsured event occurred.
Could your business pay $10,000 for damaged equipment? What about $100,000 in legal expenses? Could you pay employees and rent if the business were closed for a month?
Risks your company cannot comfortably absorb may be strong candidates for insurance.
Step 4: Compare Several Quotes
Premiums can differ substantially between insurers.
When comparing policies, make sure they have similar:
- Coverage types
- Limits
- Deductibles
- Endorsements
- Exclusions
- Policy periods
A cheaper quote is not necessarily a better deal if it provides substantially less coverage.
What to Compare Besides Premium
The annual premium is important, but it is only one part of an insurance policy.
Compare:
- Coverage limits
- Deductibles
- Exclusions
- Sublimits
- Covered locations
- Covered employees
- Additional insured provisions
- Business interruption period
- Claims-made versus occurrence structure
- Cybersecurity requirements
- Legal defense provisions
- Cancellation conditions
Also evaluate the insurer's financial strength, claims reputation, and availability of service.
Business Insurance Example
Consider a hypothetical small marketing agency with four employees.
The business rents an office, owns approximately $35,000 of computers and equipment, provides professional marketing advice, stores customer information, and occasionally meets clients at its office.
Potential insurance needs might include:
| Risk | Possible Coverage |
|---|---|
| Client slips in office | General liability |
| Fire damages computers | Commercial property |
| Covered event closes office temporarily | Business interruption |
| Client alleges professional error | Professional liability |
| Employee injured while working | Workers' compensation |
| Customer data breached | Cyber liability |
This does not mean every marketing agency needs exactly these policies. It demonstrates why insurance selection should begin with the company's actual activities.
How to Reduce Small Business Insurance Costs
Reducing insurance costs should focus on controlling risk rather than simply eliminating coverage.
Bundle Appropriate Policies
A BOP can sometimes cost less than purchasing comparable liability and property policies independently.
Compare Insurers
Pricing and underwriting appetite vary between carriers.
Choose Deductibles Carefully
A modestly higher deductible may reduce premiums, provided your business can afford the deductible after a loss.
Improve Workplace Safety
Safety training and loss-prevention procedures can reduce accidents and may support a better long-term claims history.
Strengthen Cybersecurity
Security controls such as multifactor authentication, reliable backups, employee phishing training, and software updates can reduce cyber risk.
Review Coverage Annually
Businesses change.
Your insurance should be reviewed when you:
- Hire employees
- Purchase new equipment
- Move locations
- Add products
- Enter new markets
- Buy vehicles
- Sign major contracts
- Increase inventory
- Change business activities
Paying for outdated coverage is wasteful, but failing to increase limits after significant growth can be even more expensive.
Small Business Insurance Mistakes to Avoid
Buying Only the Cheapest Policy
A low premium can come with low limits, high deductibles, restrictive exclusions, or narrower coverage.
Assuming an LLC Eliminates the Need for Insurance
A business structure can provide certain legal protections, but it does not replace insurance. A company can still suffer property losses, lawsuits, cyberattacks, and other costly events.
Underinsuring Business Property
Inventory and equipment values can increase over time. Old coverage limits may no longer be sufficient.
Ignoring Cyber Risk
Small businesses that process payments, store customer information, or rely heavily on computer systems may have meaningful cyber exposure.
Assuming Personal Insurance Covers Business Activities
Personal homeowners and auto policies can contain business-related limitations or exclusions.
Failing to Read Exclusions
Knowing what a policy does not cover can be just as important as knowing what it covers.
Questions to Ask Before Buying Business Insurance
- What specific risks does this policy cover?
- What are the major exclusions?
- What is the per-occurrence limit?
- What is the aggregate limit?
- What deductible applies?
- Are there important sublimits?
- Is the policy claims-made or occurrence?
- Are defense costs inside or outside the policy limit?
- Are all business locations covered?
- Are subcontractors covered?
- Do I need additional insured endorsements?
- Does the policy cover business interruption?
- How long does business income coverage last?
- Are cyber incidents excluded?
- What happens if my revenue or payroll increases?
- How are claims reported?
- What could cause the insurer to deny a claim?
- What changes must I report during the policy period?
Frequently Asked Questions
What insurance does a small business usually need?
Needs vary by business. General liability is common, while businesses with property may need commercial property coverage. Employers may need workers' compensation. Professional service companies may need professional liability, and businesses using vehicles may require commercial auto insurance.
How much does small business insurance cost?
There is no universal price. Premiums depend on industry, location, payroll, revenue, number of employees, limits, deductibles, claims history, property values, and other factors. Recent marketplace data shows general liability costing around $45 per month for the median customer in one large sample, but actual quotes can be substantially lower or higher.
What is the difference between general liability and professional liability?
General liability generally addresses certain third-party bodily injury, property damage, and personal or advertising injury claims. Professional liability generally addresses allegations that professional services, mistakes, errors, or negligence caused a client's financial loss.
What is a business owner's policy?
A BOP combines multiple common business coverages into one package, typically including general liability and commercial property insurance, often with business interruption coverage. Eligibility and exact coverage vary by insurer.
Do home-based businesses need insurance?
Potentially. Homeowners or renters insurance may not adequately cover business equipment, customer injuries, professional liability, inventory, or lost business income. Home-based owners should review their personal policy carefully and consider commercial coverage if gaps exist.
Is business insurance legally required?
Some types may be required depending on location, business activities, employees, vehicles, licenses, contracts, or property arrangements. Workers' compensation requirements are a common example. Verify applicable laws for the jurisdiction where your company operates.
Does general liability cover employee injuries?
Employee work-related injuries are generally addressed through workers' compensation rather than standard general liability insurance.
Does general liability cover professional mistakes?
Standard general liability insurance generally is not a replacement for professional liability or errors and omissions coverage. Businesses providing professional advice or services should evaluate their professional liability exposure separately.
How often should business insurance be reviewed?
At least annually is a useful practice, and coverage should also be reviewed after significant changes such as hiring employees, moving premises, purchasing expensive equipment, adding vehicles, entering new markets, or offering new products or services.
Small Business Insurance Checklist
Before purchasing coverage, use this checklist:
- List your company's major risks.
- Identify legally required insurance.
- Review contract and lease requirements.
- Calculate the value of business property.
- Review employee-related risks.
- Consider professional liability exposure.
- Evaluate cyber risks.
- Review business vehicle use.
- Determine appropriate limits.
- Select an affordable deductible.
- Compare several insurers.
- Compare exclusions, not just prices.
- Review insurer financial strength.
- Understand the claims process.
- Keep certificates of insurance organized.
- Review coverage annually.
Final Thoughts
The best small business insurance is not necessarily the policy with the lowest premium or the largest list of features. It is coverage that matches the real risks faced by your business at a cost you can reasonably sustain.
Begin with the events that could cause serious financial damage. A customer lawsuit, professional mistake, employee injury, vehicle accident, fire, theft, cyberattack, or prolonged shutdown can affect different businesses in very different ways.
Once you understand your risks, identify any insurance required by law, contracts, landlords, lenders, or licensing rules. Then compare insurance quotes using equivalent limits and deductibles.
Pay close attention to exclusions. Two policies that appear similar on the first page may respond very differently when a claim occurs.
Do not assume that forming an LLC, working from home, having only one employee, or purchasing a basic general liability policy eliminates every significant risk. Insurance should evolve as the company grows.
Finally, review your coverage regularly. New employees, higher revenue, additional equipment, new locations, vehicles, customer contracts, and new services can all change your insurance needs.
Good insurance cannot prevent every accident or lawsuit, but carefully selected coverage can reduce the financial damage when a covered event occurs and help a small business recover instead of facing the entire loss alone.
Disclaimer: This article is for general educational and informational purposes only and is not insurance, legal, tax, or financial advice. Insurance availability, policy wording, exclusions, costs, and legal requirements vary by insurer, location, industry, and individual circumstances. Review actual policy documents and applicable laws and consult a licensed insurance professional or other qualified adviser before purchasing or changing business insurance.